
Mon - Fri 8:00 - 6:30
Mon - Fri 8:00 - 6:30

A clear and practical guide to Medicare enrollment for 2027, explaining the key parts, important deadlines, common mistakes, and smart strategies to help retirees make confident healthcare decisions.
Many people believe Medicare is only about healthcare.
At first, Medicare is about paperwork, deadlines, timing, and decisions. Afterward, it's about understanding a system that millions of Americans depend on, yet few fully understand until they're standing at the doorstep of age 65, wondering what to do next.
Like other financial decisions, the biggest Medicare mistakes are usually small and subtle. Maybe you miss a deadline, assume enrollment is automatic, or pick a plan based on a friend's suggestion. A plan that works for someone else may not fit you.
Years later, those small choices can cost thousands of dollars. This pattern repeats in investing, insurance, retirement planning—and Medicare. The good news: once you know the rules, Medicare feels far less intimidating. Here’s what you need to know about Medicare enrollment for 2027.
As people approach retirement, their priorities shift. After years of focusing on saving and investing, preserving what you’ve built becomes the main concern. Healthcare costs are one of the biggest financial risks retirees face—even a well-prepared retirement plan can be derailed by unexpected medical bills. This is where Medicare comes in. It’s the foundation of healthcare coverage for Americans age 65 and older. However, Medicare was never intended to cover all healthcare costs. Knowing what it covers, what it doesn’t, and when to enroll can make a big difference in your retirement finances.
Medicare is a federal health insurance program primarily for:
Most people become eligible at age 65. However, being eligible doesn’t mean you’re automatically enrolled or fully covered. This is where many people get confused.
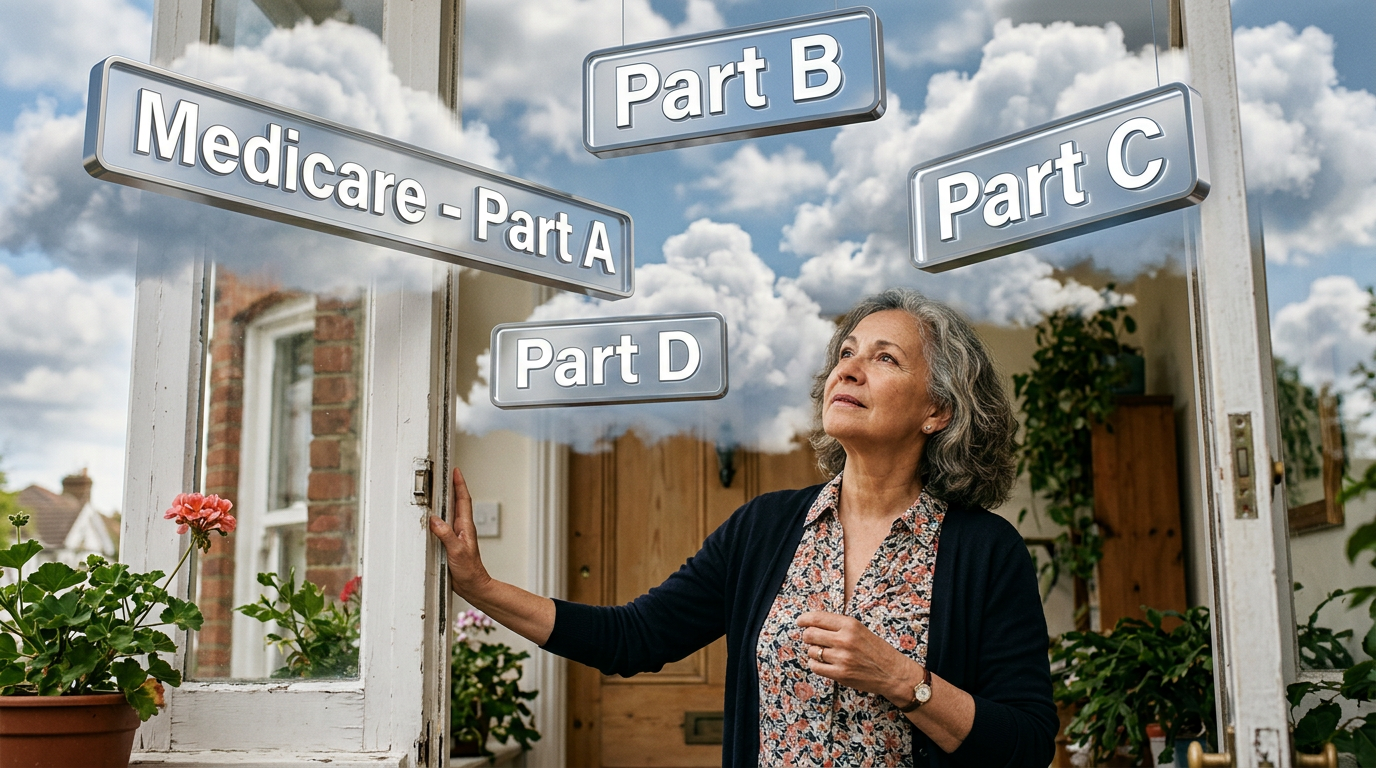
Think of Medicare as a house with four rooms.
Each room covers a different aspect of your health needs.
Part A generally covers:
Most people pay no monthly premium for Part A because they paid Medicare taxes during their working years. That’s why Part A is sometimes called “premium-free Medicare.” But keep in mind: free coverage doesn’t mean complete coverage. Part A alone leaves significant gaps.
Part B generally covers:
Unlike Part A, Part B usually comes with a monthly premium. Many retirees are surprised by this and assume Medicare is free. But healthcare in retirement still costs money—Medicare helps make those costs more manageable.
Medicare Part C and Medicare Advantage are two names for the same thing. Medicare-approved private insurance companies offer these plans.
These plans typically combine:
Many plans may also include:
Medicare Advantage has become increasingly popular because it bundles coverage for convenience. However, simplicity and flexibility can come at a cost. That’s why you should compare plans carefully.
Prescription medications can become one of the largest healthcare expenses during retirement. Part D helps cover:
Even if you don’t take many medications now, enrolling in prescription coverage can help you avoid future penalties and keep costs down if your needs change.
This is where Medicare becomes less about healthcare and much more about timing. For most people, the best time to enroll is during the Initial Enrollment Period (IEP), which lasts seven months:
Most people first become eligible around age 65. Your Initial Enrollment Period generally spans seven months:
If you miss this window, there can be consequences. The government doesn’t make exceptions for forgetfulness—the deadline is still the deadline. This lesson applies to investing, taxes, and Medicare alike.
Sometimes.
Sometimes not.
This distinction can be confusing. You may be automatically enrolled if you’re already receiving Social Security retirement benefits before age 65, but not if you’re delaying Social Security and still working. Many people wrongly believe Medicare enrollment always happens automatically. It doesn’t. Always check your enrollment status instead of assuming you’re covered. Making assumptions can be costly.
This depends largely on your employer coverage. Consider two retirees:
Mike works for a company with strong health benefits.
Sarah owns a small business and carries limited coverage.
What’s best for one person may not be right for another. Factors like employer size, group health coverage, and retirement plans all impact the best enrollment strategy. Don’t assume that just because you’re still working, delaying Medicare is the best choice. Carefully consider your own situation.
People might spend months researching investments, then just a few minutes choosing healthcare coverage. That’s the wrong order. One of the costliest Medicare mistakes is missing enrollment deadlines. Late enrollment can result in penalties that last for years—or even for life. Even a small penalty can add up over time, just like investment fees.
The problem isn't one year's penalty.
The problem is paying it every year.
This debate resembles many financial choices.
There is rarely one right answer.
The right answer depends on your circumstances.
Original Medicare generally consists of:
Many people also purchase a Medicare Supplement plan and Part D coverage.
Possible advantages include:
Possible benefits include:
Potential trade-offs may include:
The best option depends on your health, location, budget, and preferred doctors.
If someone claims there’s a universal answer, they’re likely oversimplifying.
Many people think Medicare covers everything, but it doesn’t. You’ll still have deductibles, coinsurance, and other out-of-pocket costs. Medicare Supplement (Medigap) plans help cover these gaps. If Original Medicare is the foundation, Medigap helps strengthen the rest of your coverage. For retirees seeking predictability, this extra layer of protection brings valuable peace of mind—even if it doesn’t show up on a spreadsheet.
The question sounds simple. The answer isn't. Your total Medicare costs may include:
This is why you shouldn’t focus only on monthly premiums. A lower premium doesn’t always mean lower overall costs—the cheapest option isn’t always the best value. What you pay overall matters more than what you see upfront.
Money and healthcare are both emotional topics. It’s easy to make decisions out of fear or worry—like buying too much insurance or not enough because you’re trying to save. The best Medicare decisions balance protection and affordability.
Not perfection—just protection.
A common retirement myth is that expenses drop sharply after you stop working. Some do, but many don’t—especially healthcare costs, which often rise as we age. That’s why Medicare enrollment shouldn’t be seen as a one-time event. It’s part of your overall retirement plan.
Ask yourself:
These questions matter as much as picking a Medicare plan.
The most financially successful retirees tend to share a few habits. They don’t try to make every decision perfect. Instead, they focus on avoiding big mistakes and understand that making a good decision on time is usually better than making a perfect decision too late. When it comes to Medicare, smart retirees:
Most importantly, stay involved in your healthcare decisions, because what works at 65 might not be ideal at 75.
Medicare enrollment isn’t just a healthcare story. It’s also about managing risk—protecting your years of hard work, savings, and planning. Retirement isn’t just about reaching a certain age; it’s about learning how to navigate a new set of financial decisions. Ironically, most Medicare mistakes are avoidable: the information is available, deadlines are clear, and choices are manageable. What often causes problems is simply waiting until the last minute.
As in investing, the greatest advantage often belongs not to the smartest person in the room, but to the person who prepared before everyone else realized it was necessary. So if Medicare eligibility is approaching in 2027, begin learning now.
Remember, the goal isn’t to find the perfect Medicare plan. The real goal is to create a retirement where healthcare supports your life—not becomes a source of financial stress. That’s worth planning for.
Compare ACA health plans, Medicare, life insurance, and annuities with verified local agents.
Compare My Plans →Join the HALO advisory network to receive dedicated territories and direct inquiries from consumers in your state.
Join HALO Today →