
Mon - Fri 8:00 - 6:30
Mon - Fri 8:00 - 6:30

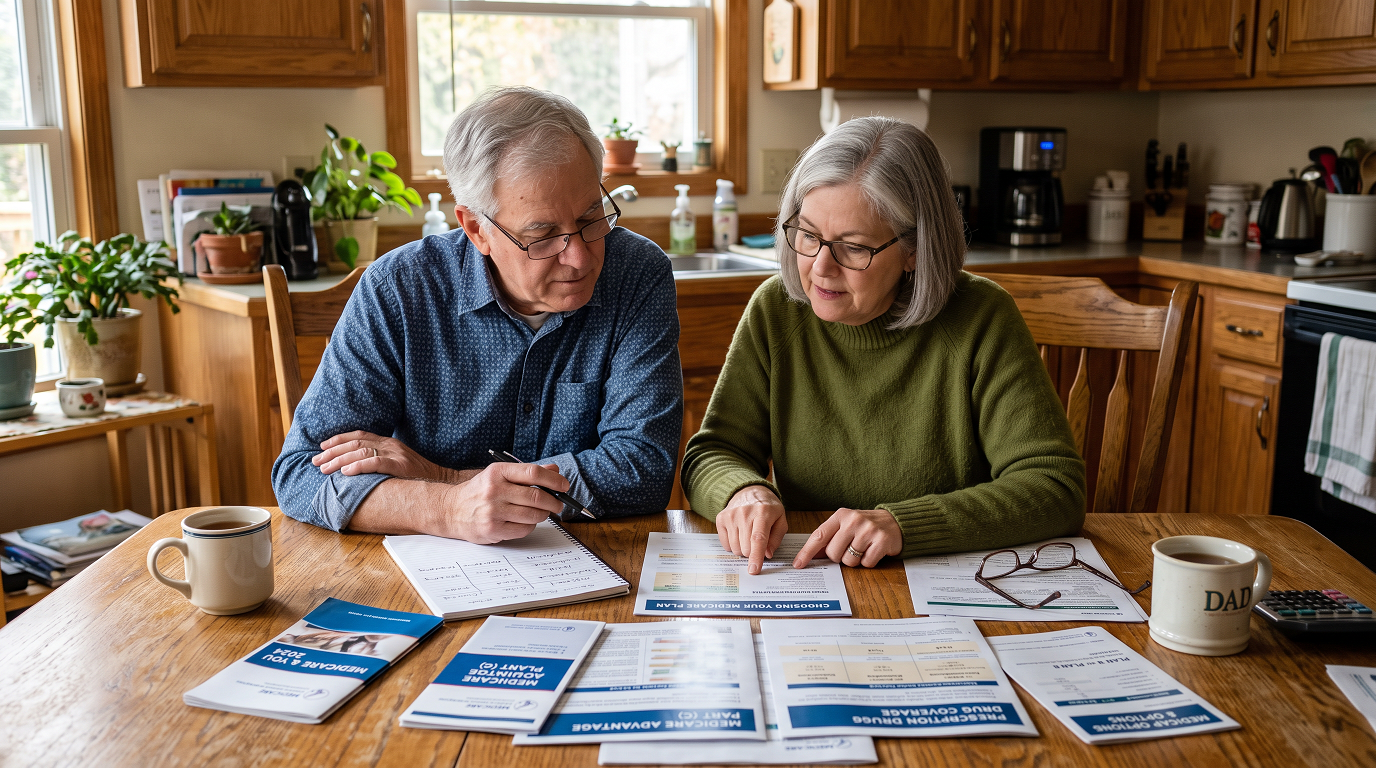
Choosing the best Medicare plan in 2027 involves more than comparing premiums and benefits. Learn how Medicare Advantage, Original Medicare, provider networks, and prescription coverage affect which plan is truly right for you.
Every October, something curious happens. Retirees who wouldn't dream of changing banks, switching churches, or moving from a home they've lived in for twenty years suddenly find themselves staring at health plan brochures from companies they've never heard of.
The brochures all seem to promise the same thing: better coverage, lower costs, and more benefits. One offers dental coverage. Another offers vision. A third advertises a grocery allowance. By the end of the afternoon, many people know more about the advertisements than they do about the plans.
The search for the "best Medicare plan" usually begins with benefits. It should begin somewhere else. It should begin with a doctor's office. Because most Medicare decisions don't reveal themselves when you're healthy. They reveal themselves when you need care.
People often ask insurance agents a question that sounds perfectly reasonable:
"What's the best Medicare plan for 2027?"
The question assumes there is a winner. There will never be a winner, as everyone's situation is different.
A retired accountant in South Carolina may choose a plan that would be a poor fit for a retired teacher in Arizona. Someone taking seven medications is solving a different problem than someone who visits a physician once a year. Medicare plans aren't products competing for first place. They're tools designed for different situations. The moment that becomes clear, Medicare starts to make more sense.
Medicare Advantage plans continue attracting millions of beneficiaries for a simple reason. They often package multiple benefits together. Most plans include:
Many also include:
From the consumer's perspective, it feels simple.
One card.
One company.
One monthly premium.
For retirees who value convenience, that's a powerful argument. The challenge is that convenience and flexibility aren't always the same.
A healthy 67-year-old with few prescriptions and routine physician visits may place a premium on low monthly costs and extra benefits. That person may rarely think about provider networks. They may never encounter a major coverage issue. For that retiree, many Medicare Advantage plans can deliver substantial value. What often goes unnoticed is that healthcare needs rarely remain frozen in time. The plan chosen at 65 is serving a different person at 75.
Ask beneficiaries managing heart disease, diabetes, cancer treatments, or multiple specialists what matters most, and many answer with a single word:
Access.
Provider access tends to grow in importance as medical needs become more complex. Original Medicare paired with a Medicare Supplement plan remains popular among retirees who value flexibility because it generally allows access to providers nationwide who accept Medicare patients. This approach often comes with higher monthly premiums. For many retirees, however, those premiums buy something difficult to measure on a spreadsheet: predictability.
One of the simplest ways to evaluate any Medicare plan is to ignore the marketing materials for a moment. Instead, make a list. Write down:
Then compare plans. The exercise is surprisingly revealing. Plans that look identical in advertisements can look very different once actual healthcare needs enter the picture. A premium that's twenty dollars lower each month may not matter much if a favorite physician isn't in-network.
Many Medicare decisions revolve around monthly premiums. Then prescriptions enter the discussion. A beneficiary taking several medications may discover enormous differences between plans.
Retirement no longer means staying in one place. Many Americans spend months visiting family, traveling, or living seasonally in different regions of the country. Healthcare follows people wherever they go.
A retiree who spends winters in Florida and summers in the Carolinas may evaluate Medicare differently than someone who rarely leaves home. Travel changes priorities.
For some retirees, broader provider access through Original Medicare becomes more valuable when distance is a factor.
The costliest Medicare mistake rarely appears in enrollment guides. It happens when people choose plans without considering how they actually use healthcare. A retiree who focuses entirely on premiums may overlook medications.
Another may focus on extra benefits while ignoring access to providers. Someone else may assume next year's coverage will remain exactly the same as it is today. Good Medicare decisions are usually practical, not emotional. They begin with doctors, prescriptions, and expected healthcare needs. Everything else comes later.
The strongest Medicare plans tend to share several characteristics. They cover the medications a beneficiary actually takes. They include the providers a beneficiary actually uses. They fit the beneficiary's budget. They continue working when healthcare needs become more complicated.
That may sound obvious. Yet every year, millions of people start with benefits brochures instead of their own circumstances. The best Medicare plan for 2027 isn't necessarily the one with the most benefits. It isn't necessarily the one with the lowest premium. And it certainly isn't the one that appears most often on television. The best Medicare plan is the one that still works when healthcare stops being theoretical and becomes personal.
At the Health And Legacy Organization (HALO), you can get personalized Medicare guidance from an independent, state-licensed insurance agent. They can help you compare Medicare Advantage, Medicare Supplement, and prescription drug plan options with confidence. No cost. No obligation. Just straightforward answers tailored to your needs.
Compare ACA health plans, Medicare, life insurance, and annuities with verified local agents.
Compare My Plans →Join the HALO advisory network to receive dedicated territories and direct inquiries from consumers in your state.
Join HALO Today →