
Mon - Fri 8:00 - 6:30
Mon - Fri 8:00 - 6:30

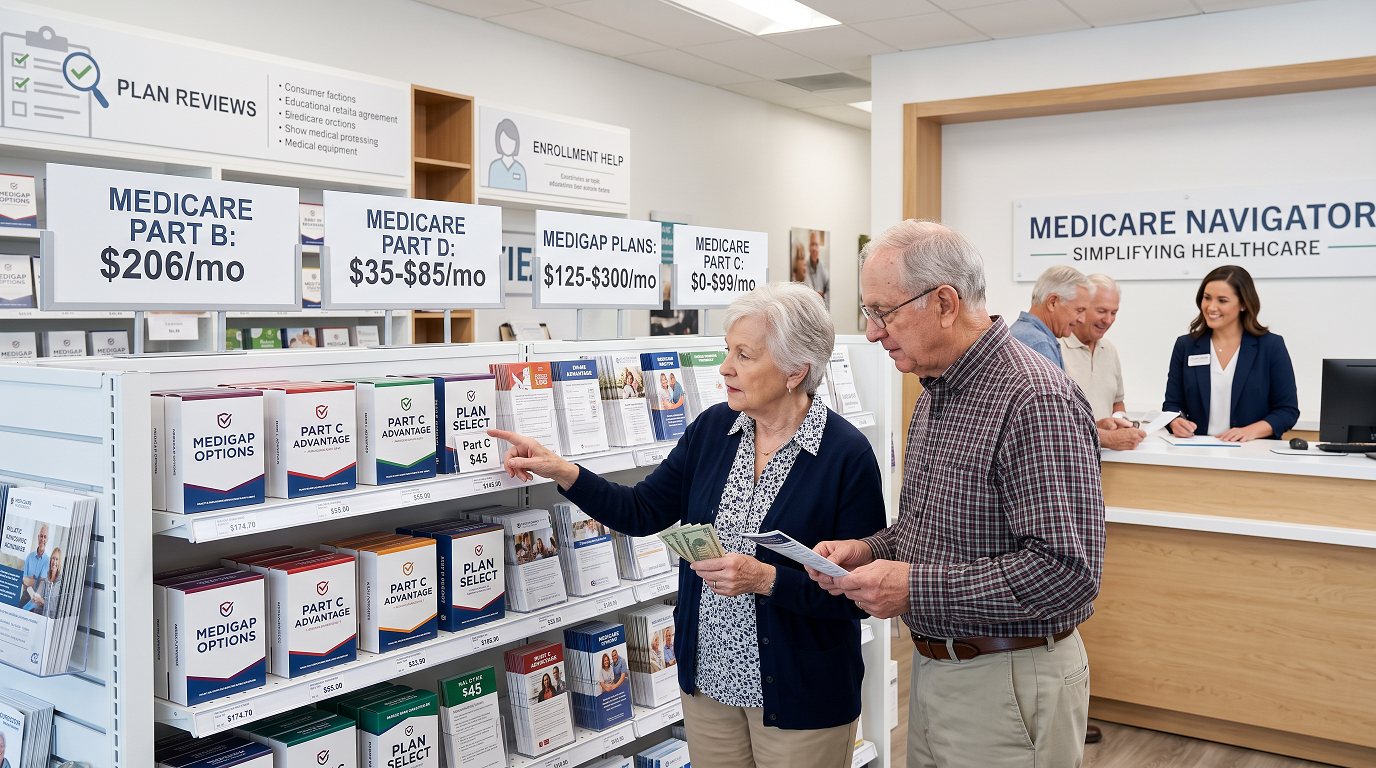
Many retirees are surprised to learn that Medicare costs involve more than a single premium. Learn how Medicare Part A, Part B, Part D, Medicare Advantage, and Medicare Supplement plans affect your monthly healthcare expenses.
For decades, workers have seen Medicare taxes deducted from every paycheck. By retirement, many assume those contributions mean healthcare will be mostly free. Then the Medicare paperwork arrives.
Suddenly, you see references to Part A, Part B, Part D, Medicare Advantage, Medigap policies, deductibles, and copayments. In reality, Medicare helps pay for healthcare. It does not eliminate healthcare costs. Understanding those costs starts with separating Medicare into its individual parts.
For most people, Medicare Part A does not require a monthly out-of-pocket premium.
Part A covers:
Most Americans qualify for premium-free Part A because they paid Medicare taxes throughout their working careers. That doesn't mean hospital care is completely free. Deductibles and cost-sharing still apply when you use services. But for monthly expenses, many beneficiaries pay nothing out of pocket for Part A.
Part B is where monthly Medicare costs become more visible.
Part B covers:
The standard Part B premium changes annually and is usually deducted directly from Social Security benefits for those already receiving Social Security. For many retirees, Part B becomes the foundation of their monthly Medicare expense. When people ask what Medicare costs each month, they often mean Part B.
Original Medicare does not automatically include comprehensive prescription drug coverage. That is why many beneficiaries enroll in a Part D plan. Monthly costs vary depending on:
Some plans have relatively modest premiums, while others cost more because they offer broader drug coverage. The key point is that prescription coverage is an additional expense many retirees overlook during initial Medicare planning.
Medicare Advantage plans package Medicare benefits through private insurance companies. Many plans include:
Some Medicare Advantage plans advertise very low monthly premiums. That attracts attention. However, premiums tell only part of the story. Healthcare expenses can also include:
A low premium doesn't always mean the lowest overall healthcare spending.
Many people enrolled in Original Medicare purchase a Medicare Supplement policy.
These plans help cover certain out-of-pocket expenses such as:
Monthly premiums differ depending on factors such as:
A Medigap policy adds to monthly healthcare costs, but many retirees choose one because it can reduce exposure to larger unexpected medical expenses later.
For many retirees, Medicare expenses often come from several sources rather than one single bill. A common setup might include:
Or:
As a result, total monthly costs may vary considerably from one person to another. A healthy retiree who rarely visits physicians may structure coverage differently than someone managing multiple chronic conditions.
The biggest Medicare expense is not always the premium. Sometimes it is the healthcare service itself. Consider two retirees. One chooses a plan with lower premiums but frequently visits specialists and requires expensive prescriptions. The other pays somewhat higher premiums but has lower out-of-pocket expenses when care is needed. Looking only at monthly premiums provides only part of the picture. View healthcare costs as a complete package, not a single number.
Many beneficiaries don't know assistance programs exist. Depending on income and eligibility requirements, some individuals may qualify for:
These programs can help reduce premiums, prescription costs, and certain out-of-pocket expenses. Every year, some eligible beneficiaries leave money on the table simply because they never apply.
Insurance companies change plans. Prescription formularies change. Provider networks change. Benefits change. A plan that offered excellent value a few years ago may not be the most cost-effective option today. Reviewing Medicare coverage annually helps many retirees identify opportunities to save money without sacrificing protection.
The question isn't really, "How much does Medicare cost per month?" The better question is:
What will my total healthcare costs look like under the coverage I choose?
For some retirees, that amount may be relatively modest. For others, monthly premiums are only one piece of a larger healthcare budget. Understanding the difference between Part A, Part B, Part D, Medicare Advantage, and Medicare Supplement plans is the first step toward estimating those costs accurately. Medicare can provide tremendous financial protection in retirement. Like any insurance program, the value often comes from knowing exactly what you're paying for and what you're receiving in return.
Compare ACA health plans, Medicare, life insurance, and annuities with verified local agents.
Compare My Plans →Join the HALO advisory network to receive dedicated territories and direct inquiries from consumers in your state.
Join HALO Today →