Volume IX • Daily Edition • Nov 11, 2026 All 50 States
Health and Legacy Organization

HALO REVIEW

The Daily Journal of Healthcare Policy, Medical Networks & Family Wealth Preservation

All 50 States Health Insurance Marketplace & ACA Subsidy Guide

State exchanges and the federal health insurance marketplace share a national benefit framework, but premium subsidies, network adequacy, and open enrollment windows are localized to All 50 States. Compare metal tiers and essential health benefits for 2026 with a licensed health insurance specialist.

Cover Story • Health Insurance Knowledge Expecting a Baby? Five Tips To Help You Prepare for Pregnancy Costs
Nov 6, 2026

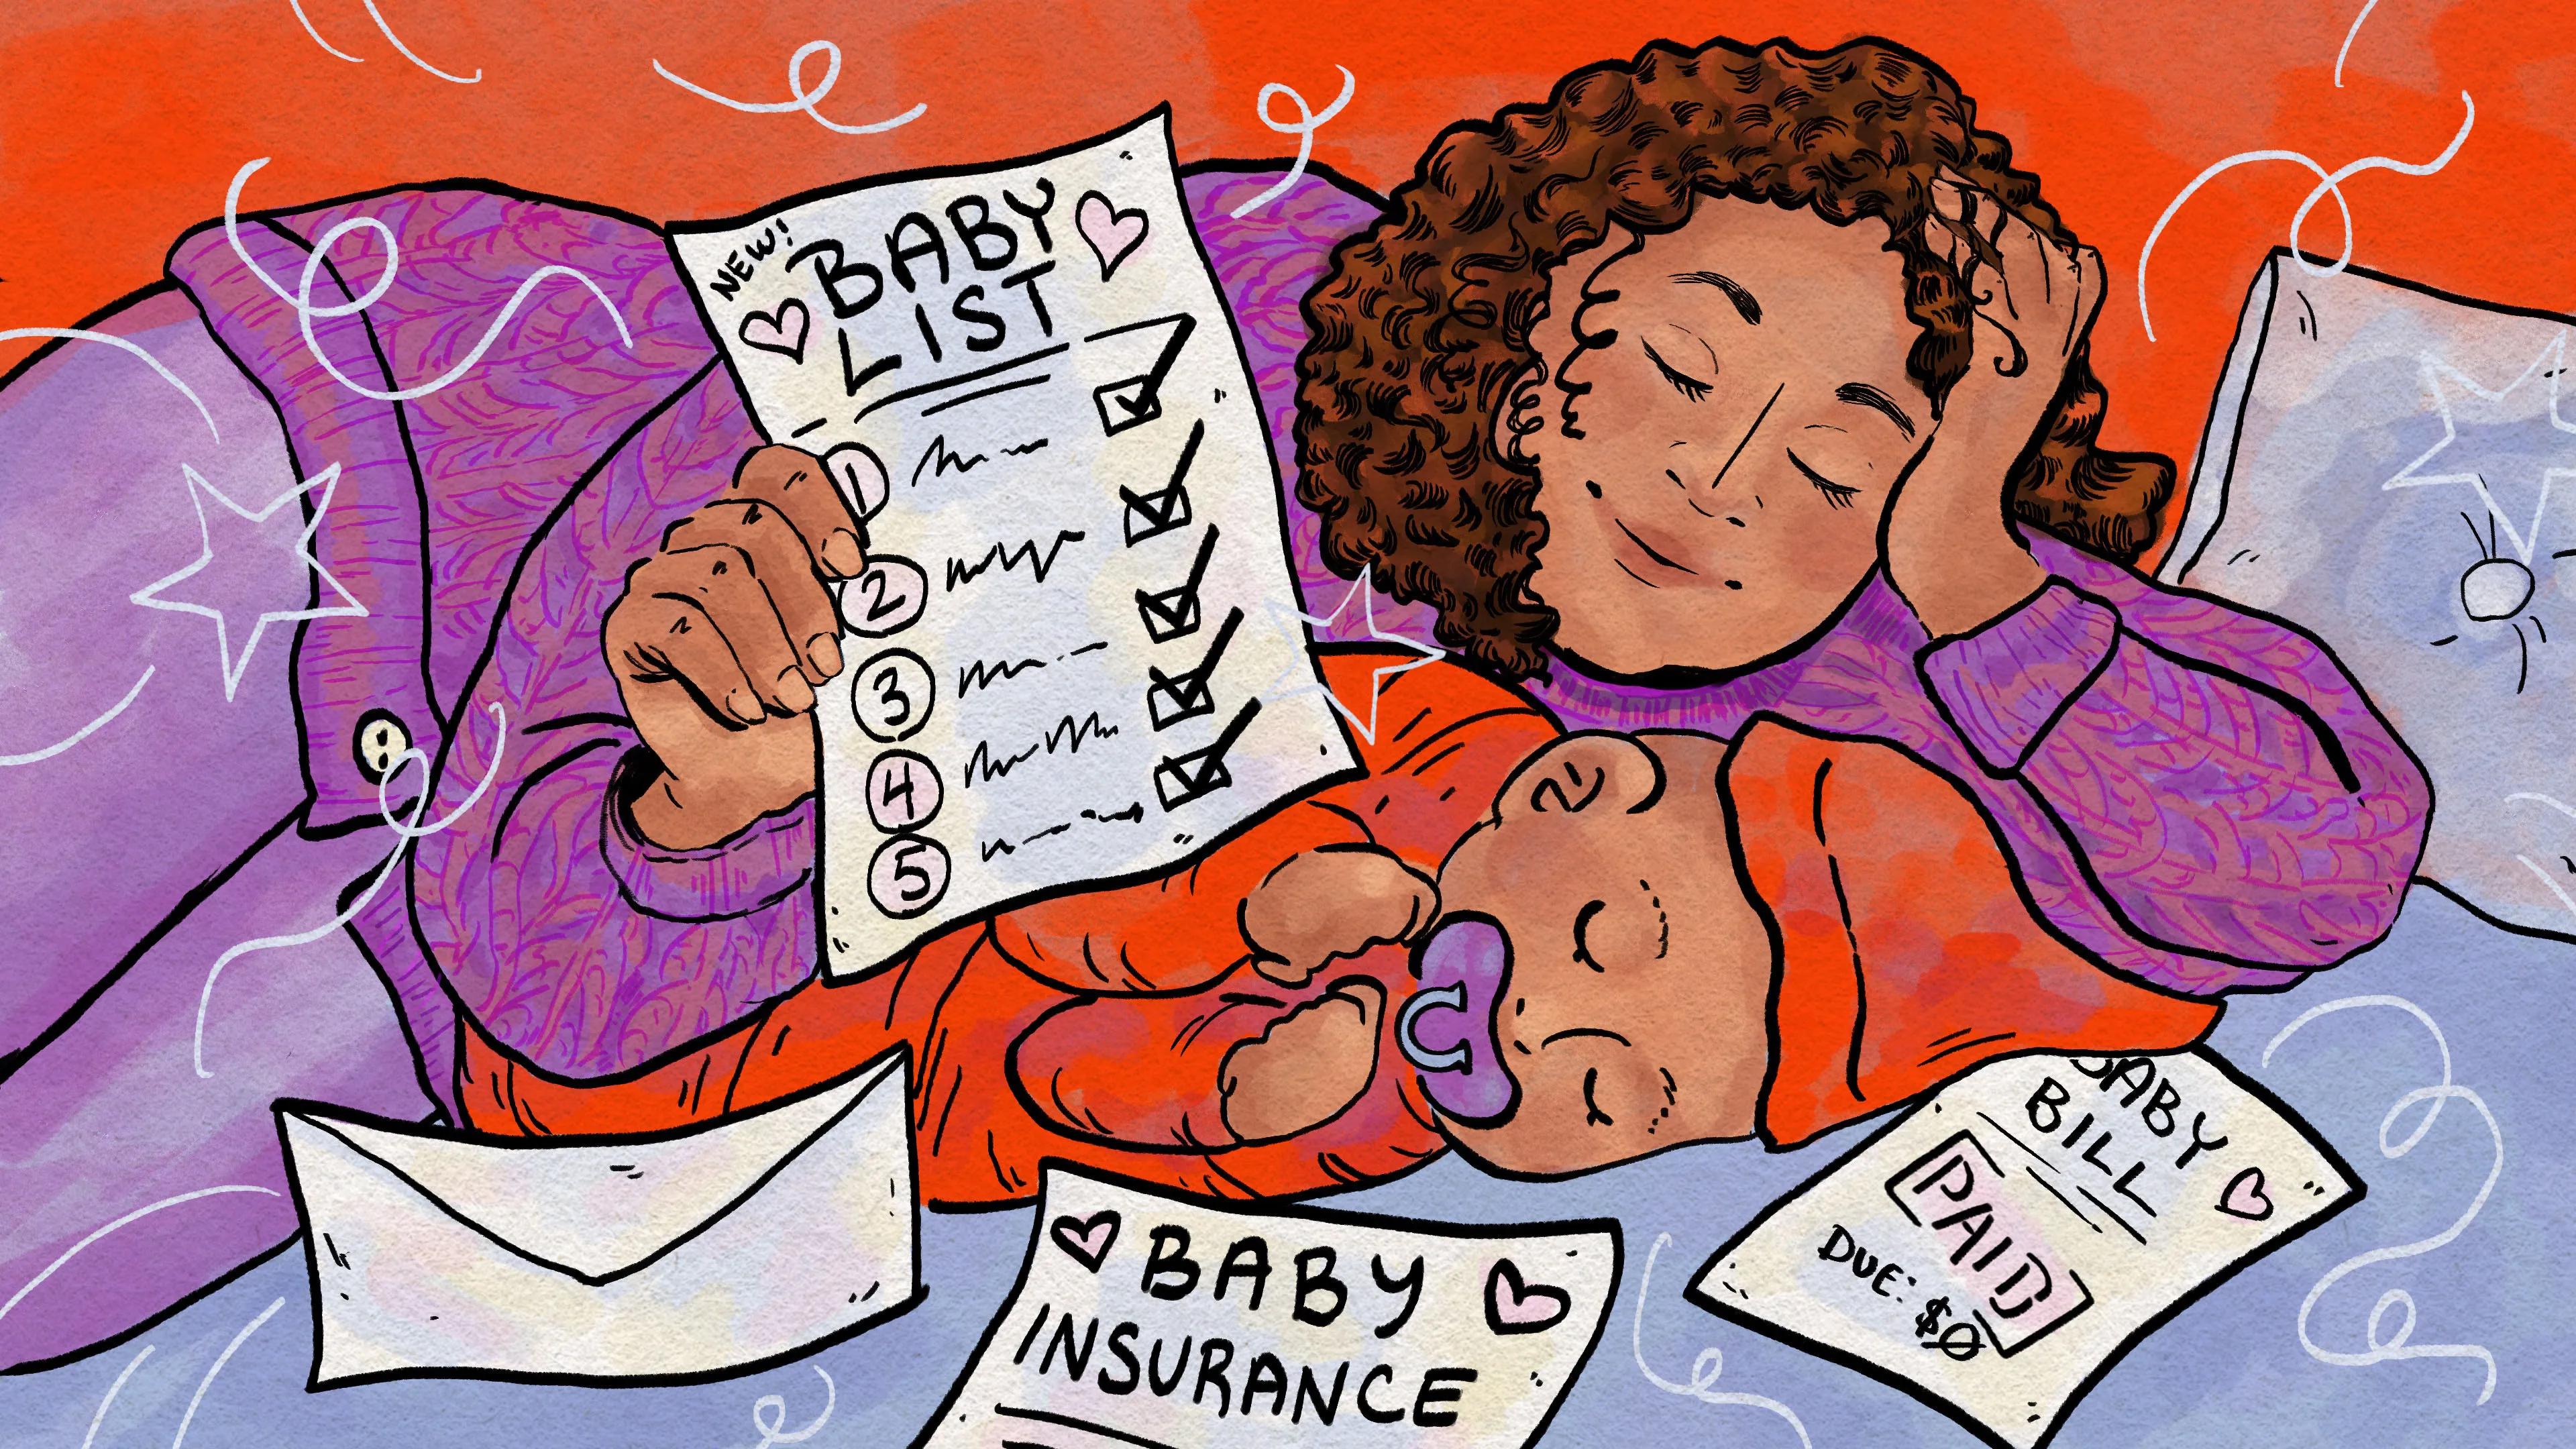
Expecting a Baby? Five Tips To Help You Prepare for Pregnancy Costs

(Oona Zenda/KFF Health News) As Grace Griffin and her husband were welcoming their long-awaited baby — a daughter — Griffin found herself worried about looming medical bills and unsure if their family could pay for the care they needed. “Th...

Advertisement • Google AdSense Placement

Latest in Health Insurance Knowledge

View all articles

The Insurance Education Directory

16 Products • Federal & State Rules

Medicare & ACA Health Insurance

Federal CMS & ACA Jurisdiction

Federal healthcare insurance programs provide standard foundational benefits across state lines, but private managed networks and plan availability remain locally designated.

Medicare Advantage (Part C)

Bundled plans approved by CMS that replace Original Medicare with private managed networks (HMO/PPO). They frequently feature $0 premiums, integrated Part D drug coverage, and allowances for dental, vision, and hearing.

Federal vs. State Rule Out-of-pocket maximums are federally capped, but provider networks, prior authorization requirements, and service areas differ by state and county.

Medicare Supplement (Medigap)

Standardized policies (such as Plan G and Plan N) that pay the 20% coinsurance and deductibles left by Original Medicare. Enrollees can see any physician or hospital accepting Medicare nationwide without network barriers.

State Underwriting Disclosures Plan benefits are federally standardized, but underwriting guidelines, guaranteed-issue birthday rules, and community ratings vary by state.

Prescription Drug Plan (Part D)

Standalone outpatient prescription coverage offered by private carriers under federal CMS guidelines. Enrollees pay monthly premiums and copays based on tier formularies.

Federal $2,000 Out-of-Pocket Cap All nationwide Part D plans enforce a strict $2,000 maximum out-of-pocket spend on covered formulary drugs per calendar year.

Family & Individual Health (ACA)

Major medical coverage compliant with the Affordable Care Act that protects against pre-existing condition exclusions and covers preventive care, maternity, and emergency hospitalization.

State-Based Marketplace Rule States either administer their own state exchange portal or use the federal healthcare.gov platform for premium tax credits.

Dental, Vision, Hearing & Group

State Regulated Market

Dental Insurance (PPO & Indemnity)

Standard 100-80-50 coverage: 100% preventive checkups, 80% basic fillings, and 50% major restorative procedures (crowns, bridges, implants) up to annual maximums ($1,000–$3,000).

State Waiting Period Laws State insurance departments regulate permissible waiting periods and fee schedule calculations based on regional Usual, Customary, and Reasonable (UCR) metrics.

Vision Insurance

Wellness policies providing copays for annual comprehensive eye exams, prescription lens coatings, and annual retail allowances for designer frames or contact lenses.

Hearing Insurance

Addresses the out-of-pocket costs of digital prescription hearing aids, custom audiologist fittings, diagnostic screenings, and replacement battery supplies.

Group Insurance (Small Business)

Employer-sponsored group benefits combining major medical, dental, and life under unified risk pools, qualifying for tax deductions under Section 125 Cafeteria plans.

Life Insurance & Final Expense

State Insurance Commissioner Supervision

Final Expense (Burial Whole Life)

Simplified whole life policies ($5,000 to $40,000) with guaranteed level premiums designed to fund funeral ceremonies, cremation costs, and remaining medical debt.

State Guaranty Association Safety State Life & Health Guaranty Associations protect death benefit claims (typically up to $300,000) in the event of an insurer's financial insolvency.

Term & Permanent Life Insurance

Provides tax-free lump-sum capital to family beneficiaries. Modern policies include Accelerated Living Benefit riders allowing access to funds for critical illness or chronic care.

Long-Term Care, Critical & Hospital

State Partnership Regulations

Long-Term Care (LTC) Insurance

Reimburses expenses incurred when a policyholder cannot perform two or more Activities of Daily Living (ADLs), covering in-home nursing aides, assisted living, and memory care.

State Long-Term Care Partnership Partnership-qualified policies allow you to protect a dollar of personal assets from Medicaid estate recovery for every dollar your policy pays in benefits.

Short-Term Care (Recovery Care)

Provides up to 360 days of temporary home care or facility benefits. Uses streamlined underwriting that allows access for seniors with minor pre-existing health conditions.

Critical Illness Insurance

Pays a direct, lump-sum tax-free cash benefit upon certified diagnosis of heart attack, stroke, or invasive cancer to offset experimental treatments and daily expenses.

Hospital Indemnity Insurance

Pays set daily cash amounts directly to the policyholder for every day admitted as a hospital inpatient. Commonly paired with Medicare Advantage to neutralize $350–$450 daily inpatient copays.

Disability & Fixed Annuities

State Guaranteed Asset Protections

Disability Insurance

Replaces 50% to 70% of gross earned income if an unexpected sickness or injury prevents you from working. Protects mortgages and long-term retirement contributions.

Own-Occupation Definition State insurance laws define the exact policy language governing when a professional qualifies as disabled relative to their specific specialty.

Annuities & Retirement Insurance

Insurance contracts structured to eliminate the risk of outliving your capital. Fixed Indexed Annuities (FIAs) credit gains based on positive index growth while guaranteeing a contractual 0% floor against market loss.

State Suitability & Free-Look Rights Every state enforces suitability regulations and mandatory 10-to-30 day free-look cancellation periods with 100% premium refunds.

Browse All 50 States

Local Rules & Advisors

Every state regulates consumer protections, rate changes, and underwriting rules independently. Select your state to review localized guidelines and find licensed resident professionals.