
Mon - Fri 8:00 - 6:30
Mon - Fri 8:00 - 6:30

: Make PUNCH part of your everyday experience. Add us to your Preferred Sources Five checks before becoming a loan guarantor Smart tips October 17, 2026 12:23 am 3D illustration of a man discussing with his friend on the financial records he must provide before he can agree to become his guarantor....
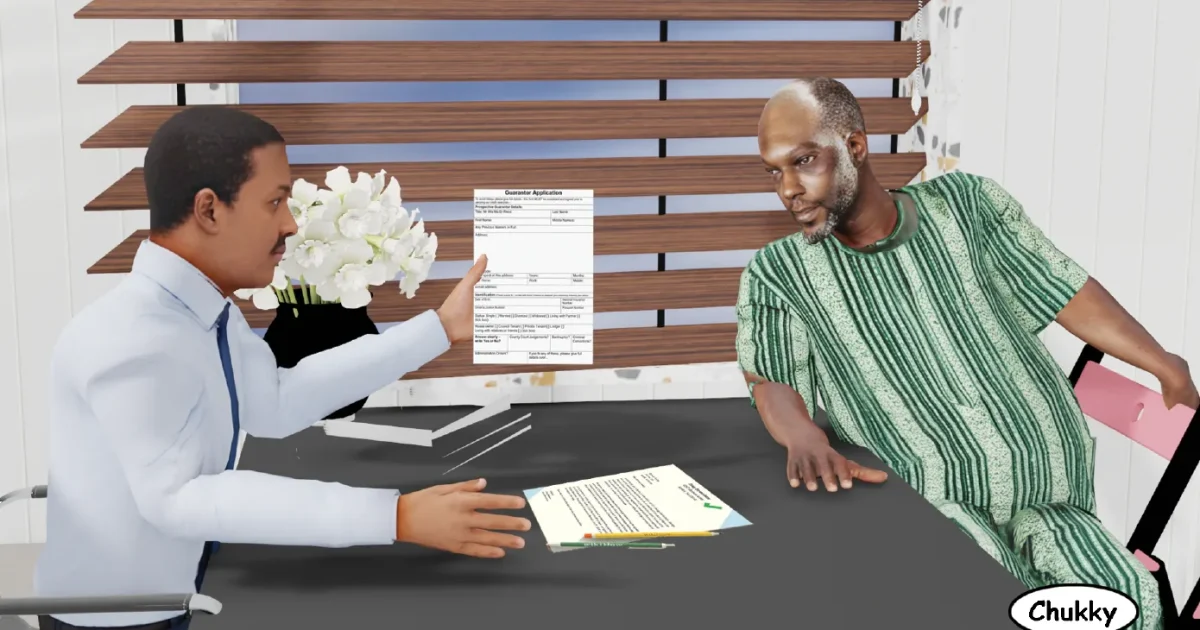
: Make PUNCH part of your everyday experience. Add us to your Preferred Sources Five checks before becoming a loan guarantor Smart tips October 17, 2026 12:23 am 3D illustration of a man discussing with his friend on the financial records he must provide before he can agree to become his guarantor. Oreoluwa Odusanya Kindly share this story: For many people, saying “no” to a close friend, colleague, or relative who asks for help can be very difficult. In the same context, turning down a close friend’s or relative’s request for financial help can make people feel guilty, uncomfortable, or afraid of damaging an important relationship.
Sometimes, the request is not for money directly but for a signature on a loan document. A relative may need someone to guarantee a business loan, while a colleague may ask for help securing a personal loan from a bank or financial institution. The borrower may insist that the arrangement is only a formality, promise to repay on time, and assure the prospective guarantor that there is nothing to worry about. For someone who trusts the borrower, signing the document may seem like a simple way to help.
However, the consequences can be significant if the borrower fails to meet the repayment terms. Becoming a guarantor is different from providing a character reference. While a character reference gives an opinion about someone’s conduct or reputation, a loan guarantee can create a legal obligation to repay a debt if the borrower defaults, depending on the terms of the agreement. A legal practitioner, Adedamola Ewumade, explained that a loan guarantee is never a casual formality or a symbolic gesture of friendship.
“It is an enforceable secondary obligation where you step into the shoes of the borrower the moment a default occurs. “The law enforces agreements, not emotional intentions or verbal promises made over lunch. If you do not have independent legal advice and a clear grasp of your maximum financial exposure, you are walking into an open legal trap,” she said.Make PUNCH part of your everyday experience. Add us to your Preferred Sources Here are things to check before agreeing to guarantee someone’s loan: Assess your own finances Before signing a guarantee, consider whether you could afford to meet the obligation if the borrower failed to repay.
Your decision should not depend entirely on the borrower’s assurance that everything will go according to plan. “Prospective guarantors should calculate their realistic maximum exposure, including accrued interest, default penalties, and debt recovery costs. “Becoming a guarantor can create a contingent liability that prospective lenders will evaluate, which can significantly damage your own credit profile and restrict your ability to obtain loans for your own needs,” Ewumade said. Investigate the borrower A person’s honesty, reputation, or business ambitions do not necessarily prove that they can afford to repay a loan.
It is important to establish whether the person asking you to guarantee the loan has a realistic plan for repaying it. “You must demand documented proof of income, recent bank statements, and tax records rather than relying on spoken assurances. Check whether the borrower has existing commitments with credit bureaus like CRC and walk away immediately if they become defensive or refuse full financial disclosure,” Ewumade advised. Understand your legal liability You should never sign a guarantee without reading the main loan agreement and understanding exactly what you may be required to pay.
“The biggest red flags in any agreement are ‘all monies’ clauses, unlimited liability, and continuing guarantee provisions that bind you to the borrower’s future debts,” Ewumade warned. “Ensure the contract specifies a strict monetary cap, defines clear termination dates, and never sign an agreement that demands your personal property or title documents as security, unless you understand the legal implications,” she added. Check what security is available Before agreeing to guarantee a loan, find out whether the borrower is providing collateral and whether the lender expects you to pledge any of your own assets.
Lenders may require a guarantor when a borrower’s income, credit history, or available collateral does not meet their lending requirements. If the borrower defaults and the available security is insufficient to cover the outstanding debt, the guarantor may still face financial liability, depending on the terms of the agreement. A legal practitioner, Ayodele Osanyinbi, advised prospective guarantors to examine the security arrangements before agreeing to guarantee a loan. “Review what security or collateral the borrower is actually providing to back the facility.
If the borrower has no skin in the game and expects your signature to serve as the sole recovery channel, you are being set up to carry an unhedged commercial burden,” she said. Know your protection and exit options Even a borrower with a reasonable repayment plan can encounter unexpected difficulties, including serious illness, disability, business failure, or death. Before signing, find out what protections, if any, are available if such circumstances arise. “Confirm whether the loan facility is covered by a valid credit life insurance policy that pays off the principal balance in the event of death or permanent disability,” Osanyinbi advised.
Kindly share this story: All rights reserved. This material, and other digital content on this website, may not be reproduced, published, broadcast, rewritten or redistributed in whole or in part without prior express written permission from PUNCH. Contact: [email protected] Make PUNCH part of your everyday experience. Add us to your Preferred Sources Stay informed and ahead of the curve!
Follow The Punch Newspaper on WhatsApp for real-time updates, breaking news, and exclusive content. Don't miss a headline – join now! Join The Punch Newspapers Channel Stay in the know—fast. Get instant alerts, breaking headlines, and exclusive stories with the Punch News App.
Download now and never miss a beat. Get the Punch News App Read PUNCH Anywhere Unlock the full print replica on any device - every page, every day. Subscribe now for instant e-edition access. Subscribe 52 minutes ago Pepsi’s yellow caps confuse consumers, spark fake product concerns 59 minutes ago Awele Elumelu’s quiet influence 59 minutes ago NSIB begins investigation as foreign-registered aircraft loses door mid-air 59 minutes ago Social media gave me creative control— Abayomi Alvin 59 minutes ago Foundation tackles classroom hunger with feeding programme $2.4bn subsidy fraud probe triggered my mother’s kidnap — Okonjo-Iweala October 17, 2026 6:06 pm Buhari wanted Osinbajo as president, ex-spokesman counters Babachir Lawal Ex-Super Eagles coach Westerhof battles colon cancer, wife seeks prayers Iheanacho reacts after making history in Turkey Toluwanisings: Hospital rejection claims spark outrage, UCH reacts Chelsea goalkeeper Martínez hospitalised after collision with Everton defender NAFDAC destroys N5.3bn fake products in one week Mob burns BRT bus for crushing motorcyclist NYSC: Five nabbed over graduates’ kidnap Pete Edochie too proud to honour industry leaders — Kola Olaiya ▲
Source: The Punch
Compare ACA health plans, Medicare, life insurance, and annuities with verified local agents.
Compare My Plans →Join the HALO advisory network to receive dedicated territories and direct inquiries from consumers in your state.
Join HALO Today →